If you scroll through social media today, you’re almost guaranteed to stumble across a 20-something “finance bro” shouting from a rented Lamborghini that you need a six-figure salary just to start investing. Or worse, they are aggressively pushing a sketchy crypto course that promises to make you a millionaire by next Tuesday.
Let’s cut the BS right now. Welcome to the unfiltered truth about money.
Whether you just moved to the US as an immigrant, transferred your hard-earned savings from a rapidly depreciating currency, or simply have a few hundred bucks left over after paying your rent and groceries, you do not need millions to build wealth. In fact, waiting until you have a “large amount” of money to start investing is the biggest lie told to the working class.
The US financial system, despite its flaws, is actually heavily built to reward people who start small but stay remarkably consistent.
Here is your comprehensive, no-nonsense guide to making your “little” money work aggressively hard for you in America. No jargon, no complex charts—just actionable steps.
Step 1: Stop the Bleeding (The “Boring” Debt Reality)
Before we even talk about making money, we have to talk about losing it.
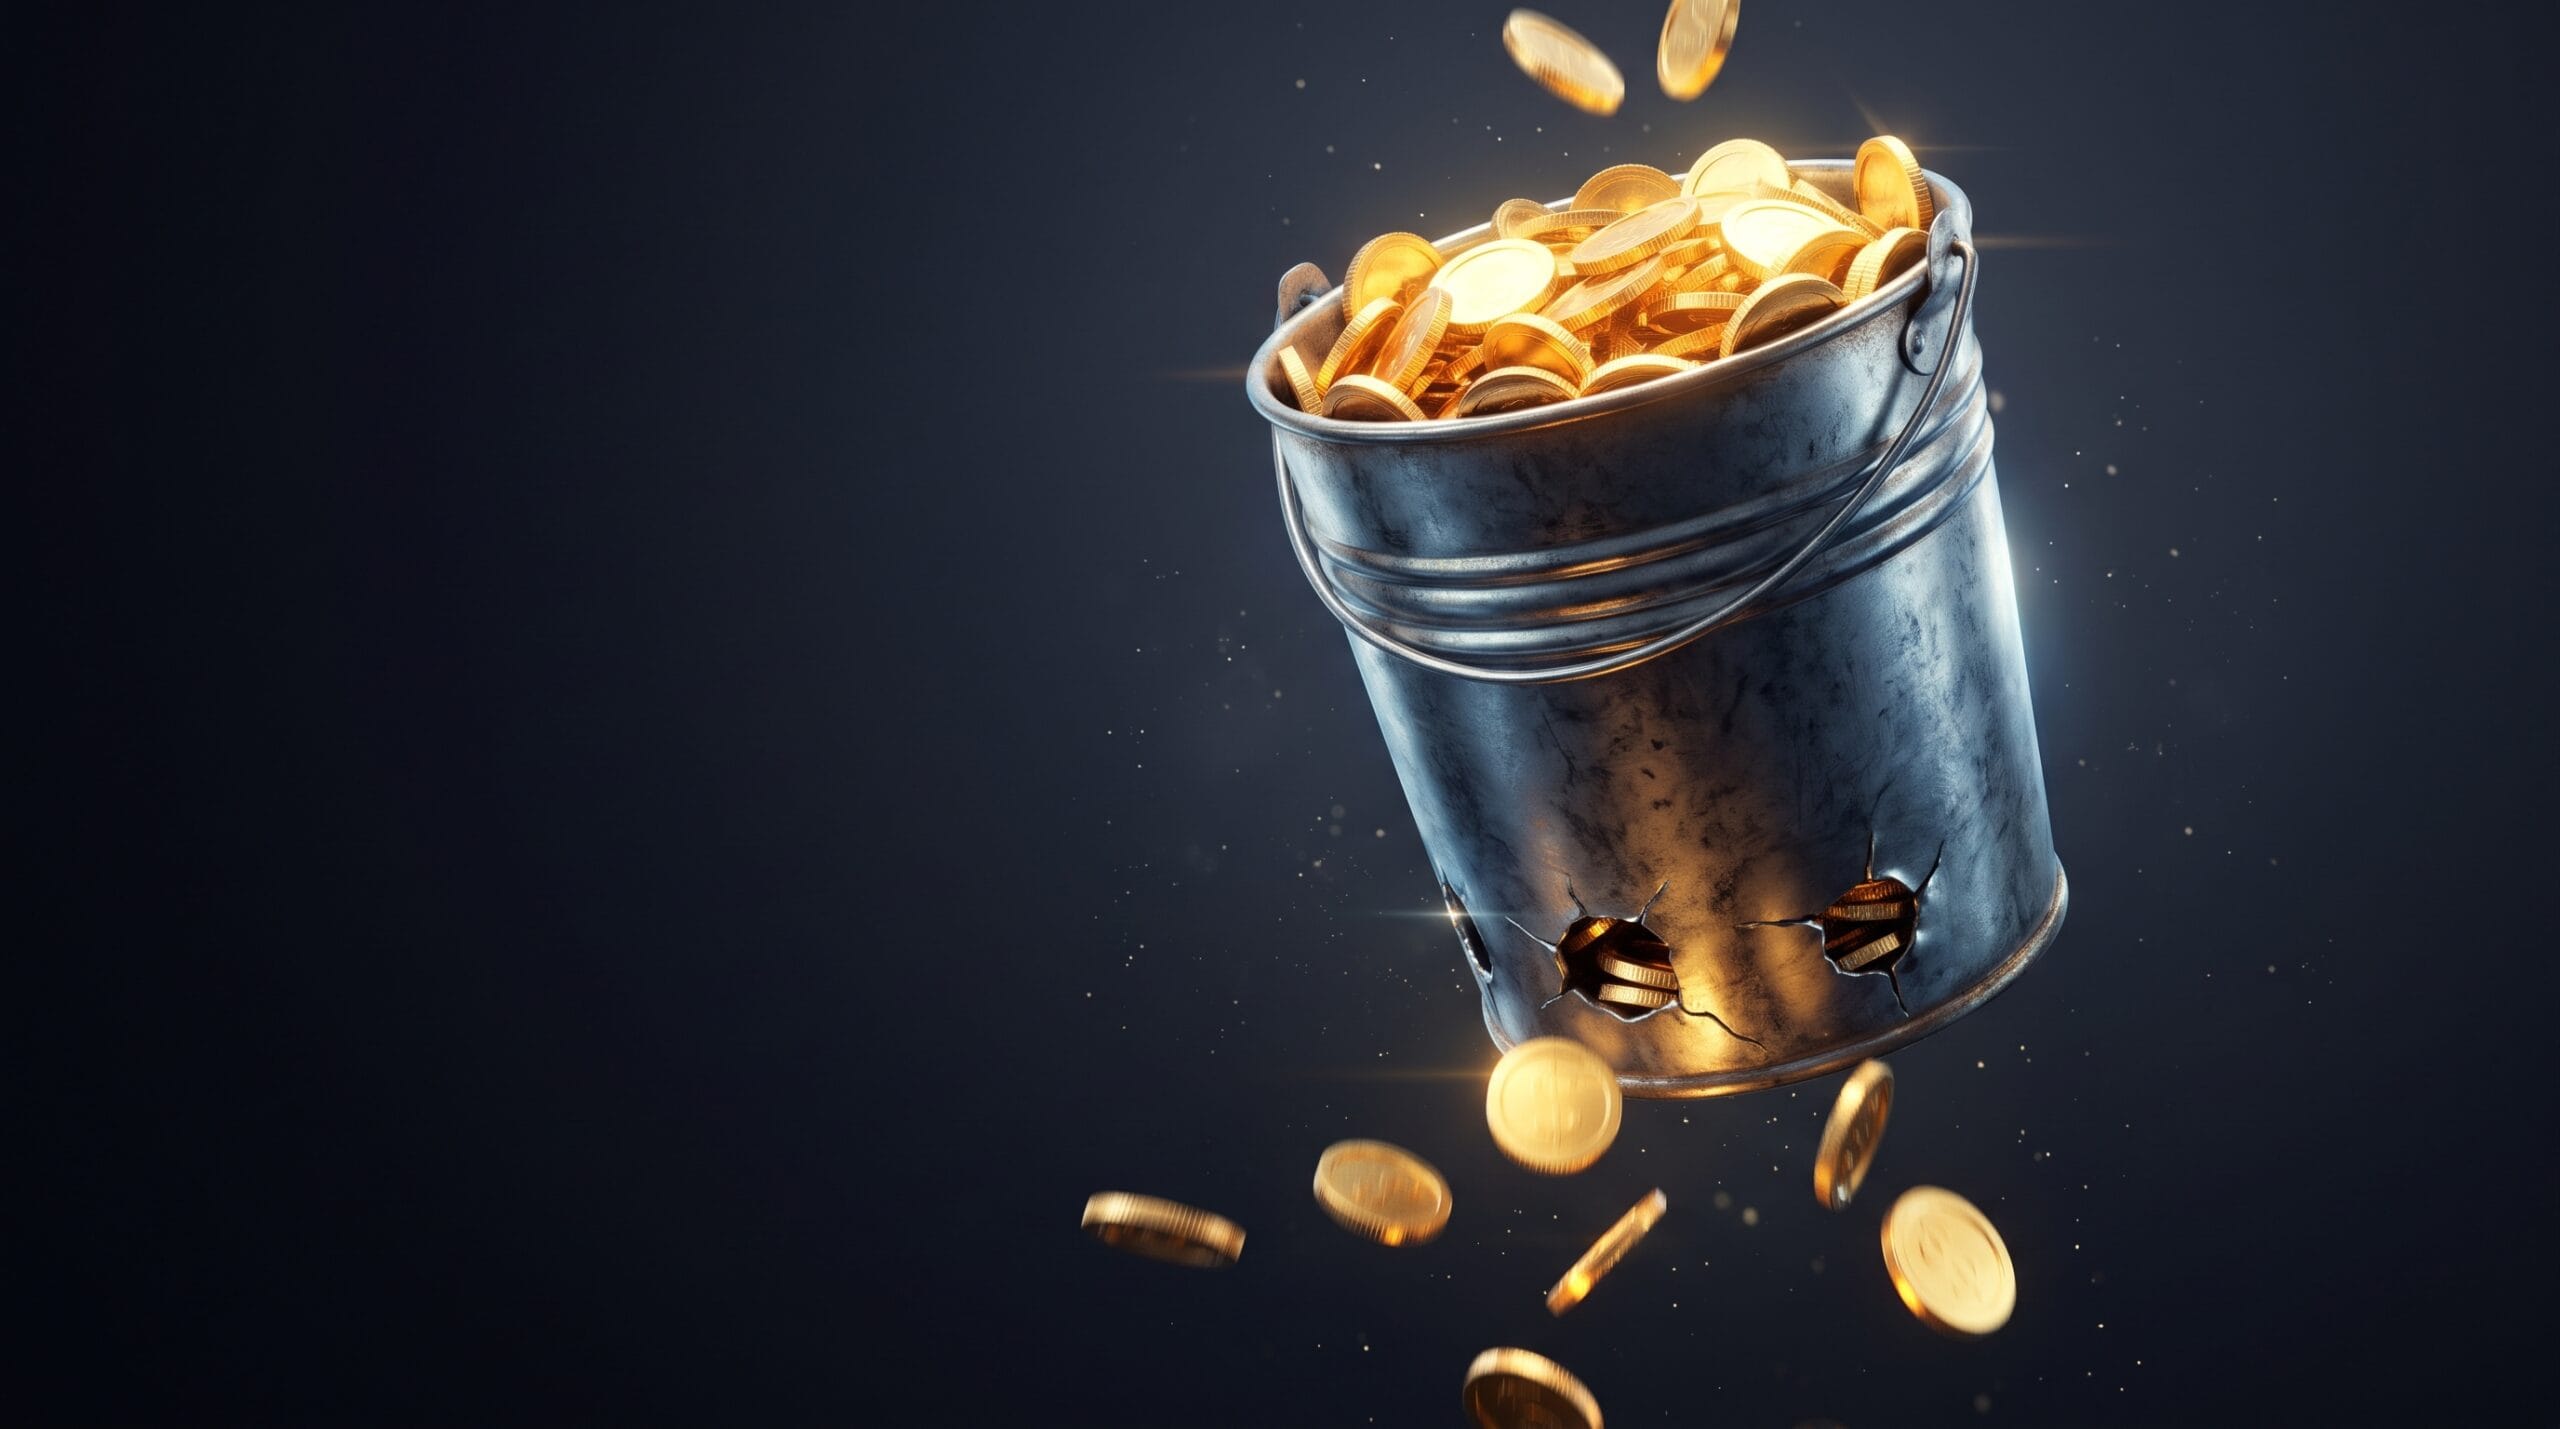
Imagine you are trying to fill a bucket with water, but there are massive holes in the bottom. That is what trying to invest while having high-interest credit card debt looks like. Before you try to make a 10% return in the stock market, you need to look at your credit cards.
If you are carrying a balance at a 24% interest rate (which is standard in the US right now), no investment in the world will save you. Earning 8% in the stock market while paying 24% to Chase or American Express means you are mathematically moving backward every single day.
The Fix: Attack your high-interest debt aggressively. Paying off a credit card with a 24% interest rate is quite literally a guaranteed 24% tax-free return on your money. You will not find that kind of guaranteed return anywhere else on Wall Street. Stop looking for the next hot stock and start crushing that debt.
Step 2: Stop Leaving Free Money on the Table (The HYSA Rule)
Let’s talk about the money you already have—your emergency fund or the cash you are saving for next year’s expenses.
If your money is sitting in a standard checking or savings account at a big traditional bank earning 0.01% interest, you are quietly getting robbed. Inflation in the US means the cost of living goes up every year. If your money isn’t growing to keep up with inflation, its purchasing power is shrinking.
The Fix: You need a High-Yield Savings Account (HYSA). Online banks like Ally, Marcus by Goldman Sachs, Discover, and SoFi currently offer around 4% to 5% Annual Percentage Yield (APY).
Let’s do the math: If you have $5,000 sitting in a big bank at 0.01%, you’ll earn a pathetic $0.50 in a year. If you move that exact same $5,000 to an HYSA at 4.5%, you’ll earn $225 in a year.
It requires zero risk, the money is FDIC-insured (meaning the US government protects your money up to $250,000 even if the bank goes bankrupt), and it takes about 10 minutes to open an account on your phone. It is literally free money just for parking your cash in a smarter spot.
 Step 3: Buy “Slices” of the Biggest Companies (Fractional Shares)
The biggest mental barrier for new investors is price. You might look at a single share of a massive tech company or an index fund, see a price tag of $400 or $500, and think, “I can’t afford to invest. I only have $50.”
Enter the magic of Fractional Shares.
Modern brokerages like Robinhood, Fidelity, Charles Schwab, and M1 Finance allow you to buy pieces of a stock. If a stock costs $500 and you only have $5, you can buy exactly $5 worth of that stock. You own a fraction of it.
What should you buy? Do not try to be the Wolf of Wall Street. Stock picking is a dangerous game for beginners. Instead, invest in an S&P 500 ETF (Exchange-Traded Fund), like VOO or SPY.
When you buy VOO, you are not buying one company; you are essentially buying a tiny, pre-packaged basket of the 500 largest, most successful companies in the United States (Apple, Microsoft, Amazon, Google, etc.). If one company fails, the other 499 are there to hold up your money.
Historically, the S&P 500 returns an average of 8-10% per year over the long term. Your job isn’t to time the market; your job is to buy a slice of the American economy every month and let it grow.
Step 4: The Automation Hack (Pay Yourself First)
The reason most people fail at investing is that they rely on willpower. They say, “I’ll invest whatever money is left at the end of the month.” Spoiler alert: There is never any money left at the end of the month. Life gets in the way.
The Fix: You have to “Pay Yourself First.” Set up an automated transfer on payday. If you get paid on the 1st of the month, set up your brokerage account to automatically pull $50, $100, or whatever you can afford on the 2nd of the month.
Treat your investment account like a non-negotiable monthly bill, just like your electricity or internet. If you don’t see the money in your checking account, you won’t spend it. This completely removes the emotion and hesitation from investing.
Step 5: The Ultimate Tax Cheat Code (The Roth IRA)
If you plan to stay in the US for the long haul, you need to understand tax-advantaged accounts. If you don’t, you’ll give a massive chunk of your future wealth back to the government.
The crown jewel of American investing for regular people is the Roth IRA (Individual Retirement Account).
How it works: You put money into a Roth IRA that you have already paid income tax on (money from your regular paycheck). You invest that money in ETFs or stocks inside the account.
The Magic: All the money it makes over the next 10, 20, or 30 years grows completely tax-free. And when you retire (after age 59 ½), you can withdraw all the money—including millions of dollars in profits—and Uncle Sam cannot touch a single dime of it. It is 100% tax-free income.
Even better? If an emergency happens, you can withdraw your contributions (the original money you put in, not the profits) at any time without penalty. It is the most powerful wealth-building tool available to the middle class.
Step 6: Don’t Want to Think About It at All? Use a Robo-Advisor
Maybe you read all of the above and thought, “This still sounds like too much work. I just want someone to do it for me, but I don’t have enough money to hire a private wealth manager.”
That’s fine. You can use a Robo-Advisor like Betterment or Wealthfront.
You download the app and answer five minutes of questions about your age, income, and risk tolerance (e.g., “Are you investing for retirement in 30 years or to buy a house in 5 years?”). The algorithm then builds a perfectly diversified portfolio for you and automatically manages it. You just link your bank account, set a monthly deposit of $20 or $100, and literally delete the app and forget about it. They charge a tiny fee (around 0.25%), which is practically nothing compared to the value they provide for beginners.
The Unfiltered Verdict
Building wealth in America isn’t about wearing a suit, working on Wall Street, or hitting the jackpot on a meme coin. It is about average people doing remarkably boring, consistent things over a long period of time.
The biggest asset you have right now isn’t your income; it is your time.
Compound interest is the eighth wonder of the world, but it needs time to work its magic. Every year you wait for the “perfect time” or a “bigger salary” to start investing, you are robbing your future self of thousands of dollars.
Stop waiting. Download an app today. Open an HYSA. Set up an automated $50 transfer. Plant the seed now. Time is the one currency you can never earn back—spend it wisely.
Disclaimer: The content provided on UnfilteredDose is for educational and informational purposes only and does not constitute financial, investment, legal, or tax advice. Investing involves risk, including the potential loss of principal. Past performance is not indicative of future results. We are not certified financial planners or advisors. Always conduct your own research or consult with a licensed financial professional before making any investment decisions.